
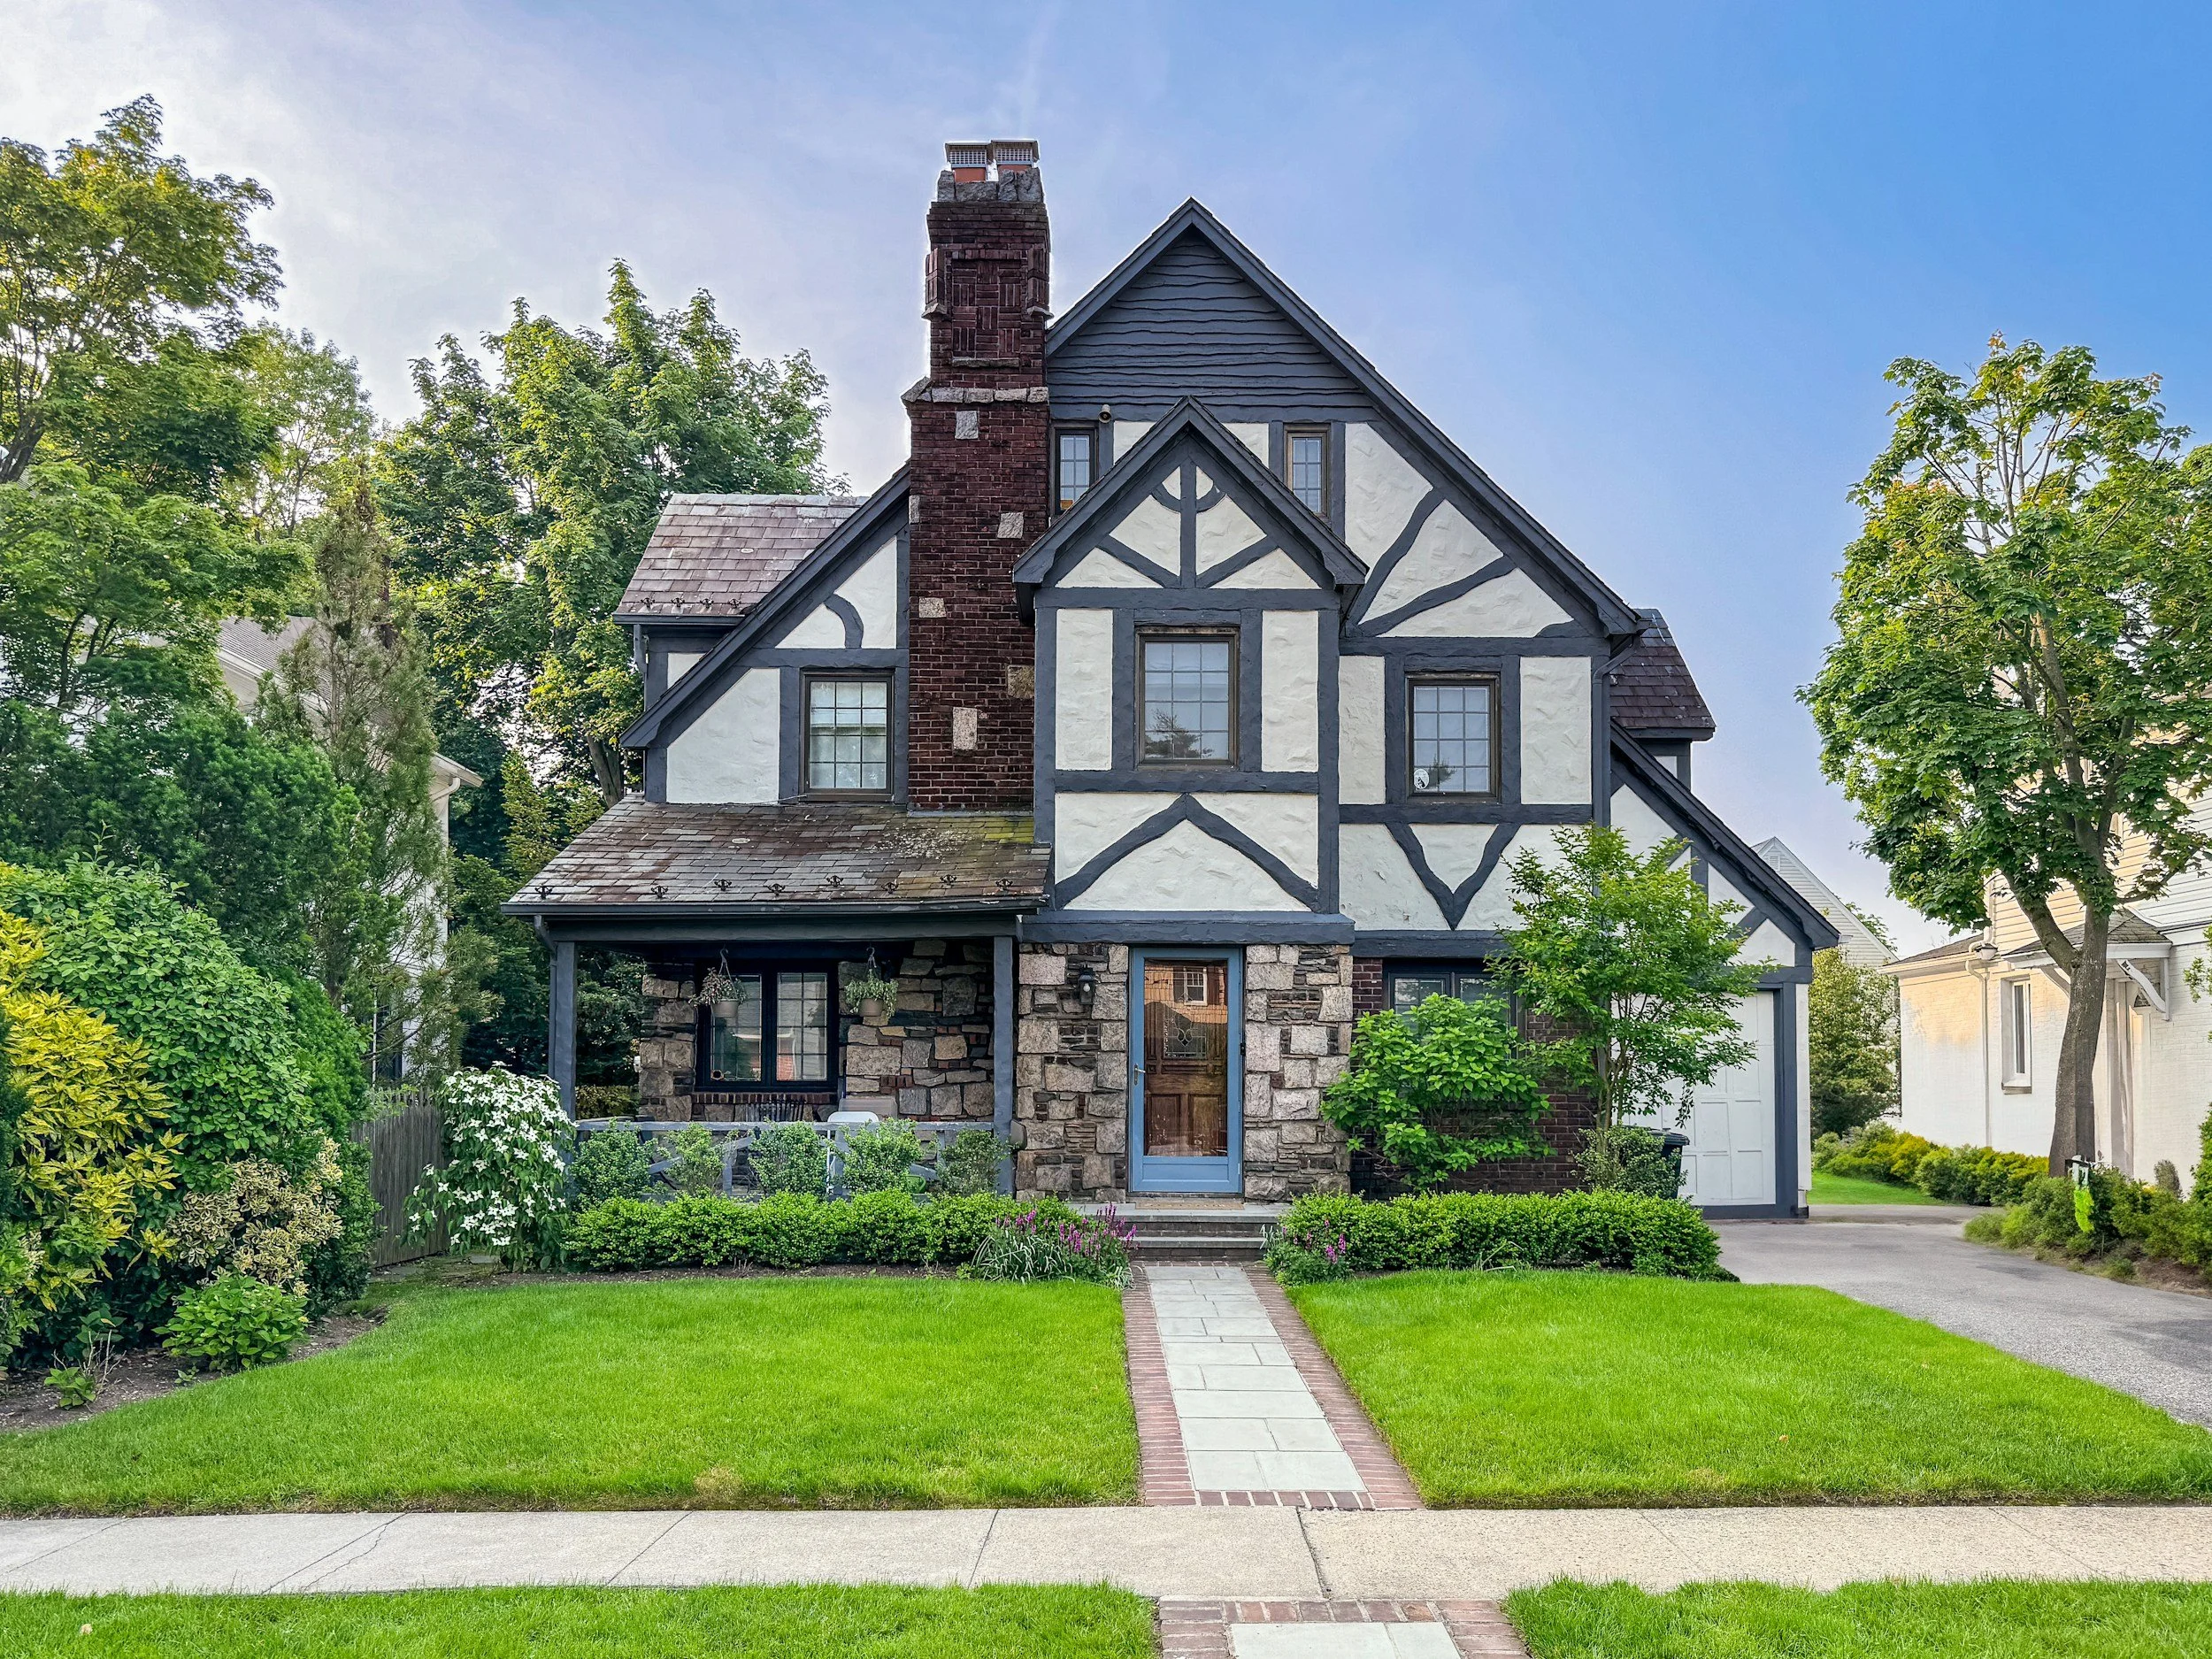
Homeowners insurance for Chardon and Geauga County homes
We quote your home with multiple insurance companies and show you the options side by side. Before we quote anything, we ask about the house itself, because the right policy for a 1920s farmhouse on a well is not the right policy for a ten-year-old colonial in a subdivision.

A veteran family-owned agency in Chardon
MC Insurance Group is run by Michael and Sarah Began, a husband and wife team with close to 30 combined years in the insurance industry. When you call, you get one of us.
We're Geauga County locals raising our two boys in Chardon. We shop your coverage with multiple carriers at no cost to you, and we never pressure anyone into a policy.
Meet the Began familyWhat a homeowners policy covers
Dwelling. The house itself, up to the limit on your policy.
Other structures. Detached garages, barns, sheds, fences.
Personal property. What is inside.
Loss of use. Living costs if a covered loss makes the house unlivable.
Personal liability. If someone is hurt on your property or you damage someone else's.
Medical payments. Small injuries to guests, regardless of fault.
What it does not cover matters just as much. Flood is never covered by a standard homeowners policy. It is a separate policy. Wear and tear, and damage from lack of maintenance, are not covered either.
What we look at on homes around here
Snow and ice
Chardon sits in the snowbelt. We check how your policy treats damage from the weight of ice and snow and from ice dams, because that is a claim people here actually have.
Wells, septic, and sump pumps
If you are on a well and septic system, we also look at service line and equipment breakdown options for the pump and the lines.
Barns, outbuildings, and detached garages
On a property with a pole barn and a detached garage, that may not be enough. We ask what is out back before we quote.
Wood stoves and outdoor boilers
Tell us about them. They affect which companies will write the home, and leaving them off an application is a bad idea.
How your roof gets paid
Some policies pay to replace a damaged roof. Others pay the depreciated value once the roof reaches a certain age, which can leave you with a large bill. Two quotes can look the same and differ on this one point. We show you which is which.
Rebuild cost, not sale price
Your dwelling limit should reflect what it costs to rebuild the house, which is a different number from what it would sell for. We run a replacement cost estimate with every quote.
What affects the price
Roof age and condition, your claims history, the deductible you choose, the age of the plumbing, wiring, and heating, and how far the house is from a fire station and a hydrant, which matters on rural roads in Geauga County. Putting home and auto with the same company often lowers both, and we quote it both ways so you can see the difference.
What to have ready for a quote
Your current declarations page, if you have one
The year the roof was last replaced
Any updates to plumbing, electrical, or heating, with rough years
Any claims in the last five years
What is on the property besides the house
Don’t have all of it? Call anyway. We can work with what you know.
Or call 440-901-6195. Evening and weekend appointments available.